Key summary:
- Major life transitions often reveal planning needs clients may not recognize yet.
- The most meaningful advisory relationships begin with understanding what is changing in a client's life.
- Personalized planning helps connect today's decisions to long-term aspirations.
Clients rarely wake up one morning and decide they need more personalized financial planning.
Instead, they reach out because something in their lives has changed. Perhaps a child is heading to college. A parent suddenly needs care. Retirement is no longer a distant concept but an approaching reality. A promotion has increased both income and responsibilities. A business is being sold. An inheritance is on the horizon. Or a family is navigating a major transition, such as marriage, divorce or the loss of a loved one.
These events may prompt the initial conversation, but they often signal something deeper: a need for clarity, confidence and a financial strategy that reflects evolving priorities.
For financial professionals, these moments create an opportunity to move beyond transactions and create more meaningful, personalized relationships. The event itself may be the catalyst. Understanding what it means to the client is where the real value begins.
Major transitions rarely happen in isolation
Financial decisions are hardly ever tied to a single event.
More often, people find themselves navigating several significant changes simultaneously. A client approaching retirement may also be supporting aging parents and helping adult children establish financial independence. Another may be balancing career growth, homeownership and family planning. Someone anticipating an inheritance may also be thinking about retirement income, healthcare costs and the legacy they hope to leave behind.
The milestone is rarely the entire story.
More often, it introduces new responsibilities, competing priorities and decisions that can reshape a household's financial picture.
In many cases, people focus on the immediate challenge sitting directly in front of them. Advisors have the opportunity to step back, identify the broader implications and help clients understand how one decision may influence many others. A conversation that begins with a job change can quickly expand into discussions about retirement savings, protection strategies, tax considerations and long-term goals.
Recognizing the signals beneath the event
Certain experiences tend to change how people engage with their finances.
Career advancement, becoming a parent, caring for aging family members, approaching retirement, receiving an inheritance or experiencing a relationship change all have the potential to alter financial priorities and behaviors. These moments frequently invite a closer look at existing plans and future objectives.
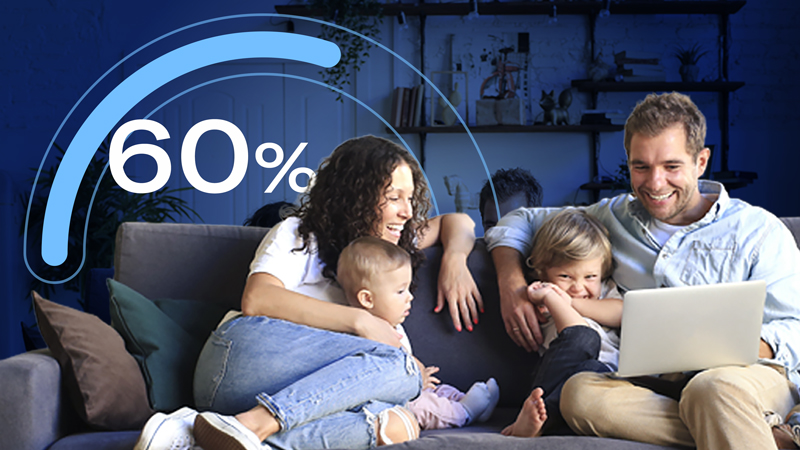
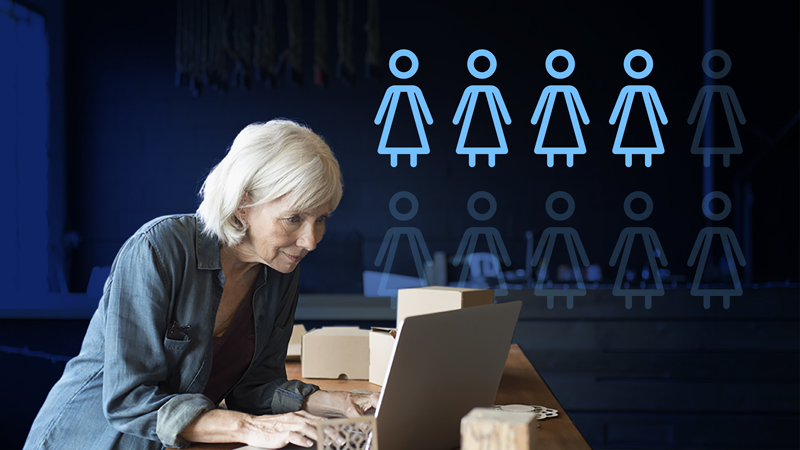
One pattern that emerged from the Women, Money and Relationships study is that pivotal personal transitions often increase financial engagement. Events such as parenthood, divorce, widowhood and nearing retirement frequently prompted nearly 60% of women to become more involved in financial decision making and seek greater participation in planning discussions. Yet, fewer than four in 10 women are confident about reaching their financial goals.1
What matters is not simply identifying the event itself. It's understanding what the event represents.
A home purchase may symbolize independence for one client and multigenerational support for another. A new job may present opportunities for wealth accumulation, while also raising questions about retirement benefits or balancing competing financial goals. An inheritance may create opportunity, but it can also introduce family dynamics, emotional considerations and important planning decisions.
The circumstances may differ, but the underlying need is often similar: people are looking for guidance that helps them navigate change with greater confidence.
Personalization begins with understanding what matters
At its core, personalized planning starts with listening.
Across multiple Equitable studies, investors consistently expressed a desire for financial professionals who understand more than their accounts and balances. They want advice that reflects their goals, responsibilities and aspirations.
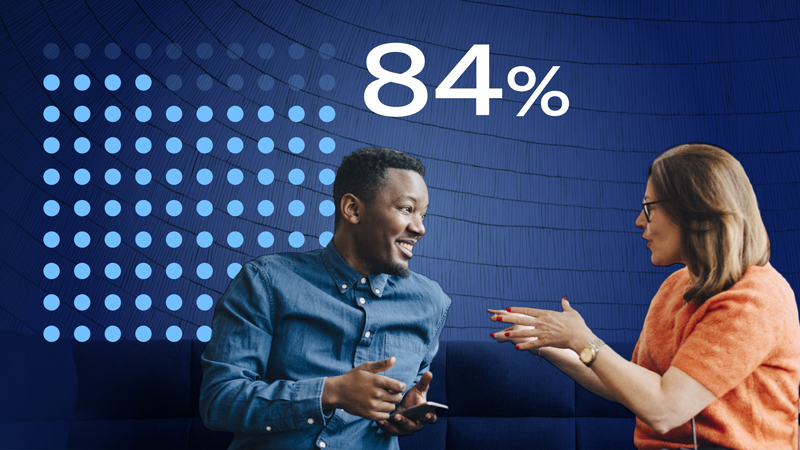
The Approaching Retirement: Getting Gen X from Good to Great study offers a powerful example. Even among investors who consider themselves knowledgeable and experienced, 84% said they want financial professionals to have a deeper understanding of their financial goals.2
That insight reflects a broader shift in expectations.
Answers to these questions often uncover priorities that traditional financial conversations can miss. They help transform planning from a product discussion into a strategy built around a person's real-world circumstances.
The goal isn't simply to solve for today's decision. It's to understand the broader story shaping tomorrow's decisions as well.
Moving from a financial question to a family conversation
Many of today's financial challenges extend well beyond the individual.
Families increasingly find themselves balancing responsibilities across multiple generations. Parents may be helping adult children while supporting aging relatives. Clients may be making decisions about caregiving, inheritance expectations or future wealth transfers. Others may be considering how they want their values reflected in the legacy they leave behind.
They require discussions about priorities, relationships, expectations and long-term objectives. The PEAK 35™: Guiding a New Generation of Wealth study found that 68% of Millennials prefer working with a human advisor or a hybrid combination of personal guidance and technology,3 reinforcing the value they place on advice that helps them navigate increasingly complex decisions.
Similarly, findings from The Great Wealth Transfer suggest that investors place significant value on trust and on working with professionals who understand their lives beyond finance alone. The study also found that 55% identified trust as the most important factor when selecting a financial advisor.4
For advisors, this presents a meaningful opportunity.
The professional who helps navigate retirement decisions today may also become a trusted resource during future conversations involving spouses, children, aging parents and future generations. When handled thoughtfully, a single planning discussion can become the foundation for a much broader relationship.
Seeing beyond the milestone
Money becomes more meaningful when it is connected to the lives people want to build.
Significant transitions have a way of bringing priorities into sharper focus. They prompt important questions about family, work, purpose, independence and legacy. They reveal where guidance, education and a broader perspective can make a meaningful difference.
For financial professionals, the most valuable opportunities often emerge long before a client asks a planning question directly. They begin when something changes:
- A new responsibility
- A new goal
- A new challenge
- A new chapter
Looking for related content?
Browse additional insights, research and advisor-focused articles that can help support other meaningful conversations and personalized planning strategies.
1 Equitable Holdings, Inc., Women, Money and Relationships Study, 2023.
2 WSJ Intelligence, Approaching Retirement: Getting Gen X From Good to Great, 2025.
3 Equitable Holdings, Inc., PEAK 35™: Guiding a New Generation of Wealth, 2025.
4 WSJ Intelligence, How to Plan for The Great Wealth Transfer, 2024.
Equitable is the brand name of the retirement and protection subsidiaries of Equitable Holdings, Inc., including Equitable Financial Life Insurance Company (Equitable Financial) (NY, NY); Equitable Financial Life Insurance Company of America (Equitable America), an AZ stock company with an administrative office located in Charlotte, NC; and Equitable Distributors, LLC. Equitable Advisors is the brand name of Equitable Advisors, LLC (member FINRA, SIPC) (Equitable Financial Advisors in MI & TN). For purposes of this discussion, advisor is used as a general term to describe insurance/annuity, investment sales, and advisory professionals who may hold licensing as insurance agents, registrations with broker-dealers, and registrations as investment advisory representatives (IAR) of registered investment advisers, respectively. Advisor in this context is not intended to necessarily refer to IAR offered fee-based financial advisory/planning services.
©2026 Equitable Holdings, Inc. All rights reserved.
GE-9127785.1 (09/2026) (Exp. 09/2030)