This article will:
- Gen X is transitioning to decumulation and needs guidance shifting from a decades-long savings mode to a sustainable income plan.
- Financial professionals are being recognized as more important. This famously DIY generation values professional experience.
- Aligning retirement goals: Gen X needs help finding the balance between lifestyle, longevity risk and their legacy goals.
It’s the question on the minds of millions of Gen Xers as they enter their retirement years: How can they balance lifestyle, longevity risk and legacy? This cohort is in their late 40s to very early 60s and is in their peak earning years and/or preparing to move into retirement. As they shift from accumulating assets to spending them down, they’ll need financial professionals (FPs) who can guide them in creating a plan that can sustain their needs — and goals — during retirement.
As a group, Gen X has always blazed their own trails, finding ways to navigate market ups and downs and modern technologies.
Now, this cohort is reaching the summit of their financial lives. They’re in their peak earning years and looking at upcoming retirement. Like any mountain descent, the path forward will require good judgment, a steady pace and an experienced financial guide. What are they looking for? In our recent study, Approaching Retirement: Getting Gen X from Good to Great, 84% of investors said a financial advisor should understand their overall goals, objectives and risk tolerance.1
Here’s a five-point framework to uncover pre-retirees’ unique priorities, deepen planning conversations and better support financial decisions.
Accumulating assets takes time, discipline and consistency, habits Gen X investors have used to their advantage, including in self-directed investing. But the pivot to decumulation – the process of withdrawing and using assets to fund retirement expenses – requires a shift in their perspective: Instead of growing wealth, the goal becomes planning for sustainable income during retirement, which requires a different approach to their next phase of life, one with clear objectives and disciplined behavior. This is where a financial professional can help them understand why and how they need to adjust their asset strategy.
This guidance should include addressing practical issues and their emotional impact. Not only do new retirees need to ensure their retirement assets can last for decades, after years of careful saving, they also must feel comfortable with the mental and emotional transition to spending those savings. A financial professional who can explain and help with decumulation planning to show how it fits into their longer-term lifestyle, and how it accounts for various risks, will have tremendous value for Gen X clients.
As retirement nears and clients begin withdrawing assets, the risk focus changes from accumulation to sustainability and navigating market movements, including potential downturns, as they begin withdrawals.
Pre-retirees need guidance in planning for inflation, healthcare costs, sequence of returns (the order in which investment returns occur over time), and how those can all affect their income stream now and in the future.
Gen Xers will be looking for advisors who can help balance their concerns about risks with feeling the need to carry on with growing their wealth. A common solution: Develop a strategy that combines guaranteed income to cover essential expenses with more growth-oriented investments that can:
- Provide protection strategies to help offset inflation and volatility
- Address discretionary spending
- Guide legacy planning

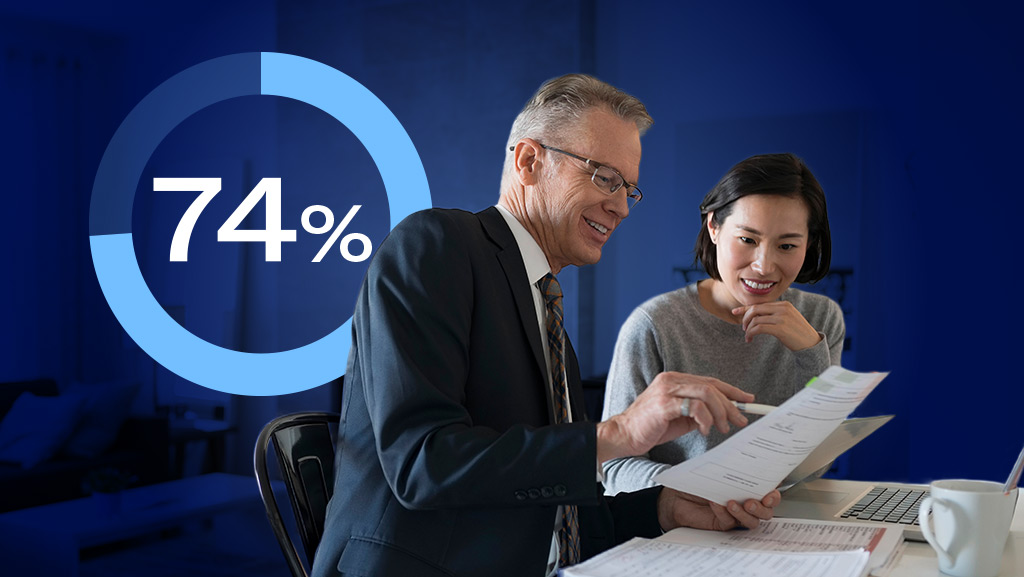
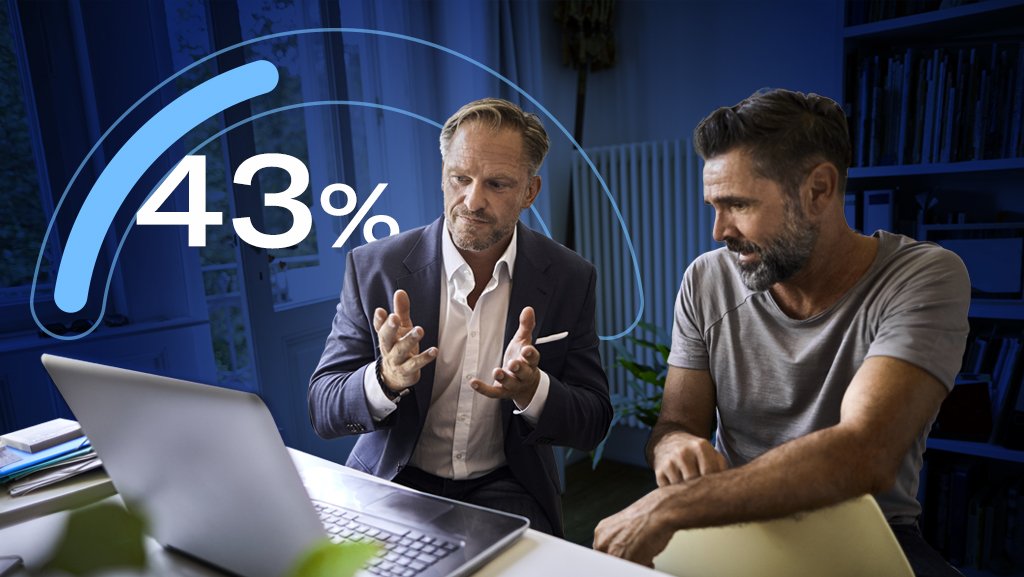
of Gen Xers prefer not to increase their risk-return mix1
Gen X is generally starting from a good place: They have decades of experience managing their money and investments and are generally well-versed in personal finance. But a generation known for its independence isn’t used to working with a financial professional.
Gen X values working with someone to guide them — but they aren’t used to it and don’t always know how or when to engage someone. FPs will benefit from being proactive in reaching out to these clients. Many Gen Xers have done the bulk of their investing and financial management on their own and still put a high value on professional advice.
For these clients, FPs should start by acknowledging what investors have built and then introduce the need for specific decumulation planning. Framing the discussion among the many challenges and pressures Gen X faces, such as job displacement, early retirement, caregiving and healthcare costs, can better demonstrate why it’s always the right time to start or re-examine what's in place. Retirement income planning really can't wait.
Without a coordinated tax strategy, assets can erode faster than clients expect. Many Gen X investors are juggling multiple 401(k)s, traditional and Roth IRAs, taxable accounts and legacy holdings, making tax diversification increasingly complex when it’s time to begin distributions.
Advisors have a critical role in creating a strategy to sequence withdrawals across account types and manage tax efficiency across tax brackets, including evaluating:
- When to draw from taxable vs. tax-deferred accounts
- How to manage required minimum distributions (RMDs)
- Whether to take advantage of Roth conversion opportunities during lower-income years
- How inherited assets may affect tax liabilities, distribution strategies and long-term income planning
It’s not one size fits all. Instead of a static withdrawal rule, Gen Xers often appreciate a dynamic, year-by-year approach that adapts to changing market conditions, evolving tax policy and shifting income needs.
Conclusion
Reaching the summit of retirement savings isn’t the end game. It is an important milestone Gen Xers have achieved. The transition to decumulation is the next stage in their journey.
This cohort already holds significant assets and has established good financial habits. FPs who understand where Gen X is coming from and how personalized financial planning can help them get where they want to go will have the edge at becoming the trusted voice to help them plan for the next phase of their life.
Explore all the Gen X financial planning insights by checking out Let’s Plan How®.
Source:
1 “Approaching Retirement: Getting Gen X From Good to Great,” WSJ Intelligence & Equitable Thought Leadership Study, August 2025.
Disclosures:
Equitable is the brand name of the retirement and protection subsidiaries of Equitable Holdings, Inc., including Equitable Financial Life Insurance Company (Equitable Financial) (NY, NY); Equitable Financial Life Insurance Company of America (Equitable America), an AZ stock company with an administrative office located in Charlotte, NC; and Equitable Distributors, LLC. Equitable Advisors is the brand name of Equitable Advisors, LLC (member FINRA, SIPC) (Equitable Financial Advisors in MI & TN).
IMPORTANT
For purposes of the discussion, advisor is used as general term to describe insurance/annuity, investment sales and advisory professionals who may hold licensing as insurance agents, registrations with broker-dealers and registrations as investment advisory representatives (IAR) of registered investment advisers, respectively. Advisor in this context is not intended to necessarily refer to IAR offered fee-based financial advisory/planning services.
©2026 Equitable Holdings, Inc. All rights reserved.
GE-9085887.1 (08/2026) (Exp. 08/2030)